Independent Jewelry Discovery Map
Where independent fine jewelry brands sell, show up, and get discovered.
Original research into where independent jewelry brands appear, and don't, across search, AI recommendations, marketplaces, editorial, retail and their own channels.
- Edition
- 2026 Edition
- Status
- Ongoing research
- Sample
- 146 brands analyzed
- Last updated
- October 2026
Non-branded Google discovery · 100-brand study
11
of 100 brands appeared in Google's first 20 organic results for at least one of their two category searches
For the category searches that describe what they sell, most of the brands we tested did not appear.
Each brand had two non-branded searches chosen from its own product language before any results were checked. 89 of 100 brands did not appear in the first 20 organic Google results for either search on the dates checked.
What “appeared” means
A brand counts as appearing when its own website is one of the first 20 organic results for at least one of its two category searches. Not appearing means its own website was not in those results for either search, in this one check. It does not mean the brand cannot be found on Google: shoppers may reach it by name, through Etsy or retailers, on social platforms, in shopping results, in AI answers or with different searches.
- The 100 brands are a curated cohort fixed on Oct 6, 2026, not a random sample, so the result describes this cohort rather than all independent jewelry brands.
- The 200 brand-search pairs use 149 distinct searches, because some brands share a search. Each distinct search was run once.
- Each search was a desktop, United States (country level) Google search in English, run through the data provider rather than a personal browser. We asked for the first 30 organic results and counted only ranks 1 to 20. Results change daily and differ by city and device; this is one snapshot.
- Two brands (Grainne Morton and Isabel Borland) each had one result that Google returned as a redirect and that could be identified only by its title (a Reddit thread). We counted both brands as not appearing because the result cannot be one of the cohort's sites. If those two are treated as not evaluable instead, 2 brands are unresolved and 87 did not appear.
- Counting the first 30 results instead of the first 20 would add 2 brands that appeared at ranks 23 and 27.
- Only organic results count. Ads, Shopping, AI Overviews, image results, social profiles, marketplaces and editorial pages were not counted as the brand appearing.
- The searches were fixed by Found & Form from each brand's own wording. Other searches would give other results.
- Excluding two brands the study classed as not independent, 10 of 98 appeared.
- Search result data: DataForSEO Google Organic SERP API. Counts were recalculated independently from the saved results.
Correction: an earlier version of this section (October 7, 2026) reported that 62.9% of 62 evaluable brands did not appear. That figure came from a different data source and could not be reproduced from retained data, so it has been withdrawn and replaced by this study. The two results are not comparable.
Why traffic alone can mislead
Search traffic can hide a discovery problem.
A brand can appear healthy in organic search while most of that demand comes from people who already know its name. Found & Form separates navigational or branded demand from the harder question: can a shopper discover the brand without knowing what to type?
Malka Jewelry
74%
Branded / navigational
5%discovery share
Semrush navigational-intent traffic vs. Found & Form manual classification of the top 50 keywords.
Adorn Pili
87%
Branded / navigational
13%discovery share
About 87% of Semrush-estimated organic traffic was branded or near-branded; the remainder is shown as the non-branded/other share.
1 · Existing demand
Someone searches the brand by name.
2 · Product discovery
Someone searches for what the brand makes.
3 · Recommendation
Search or AI surfaces the brand without being asked for it.
The Malka and Adorn Pili figures are case studies, not the aggregate estimate above. Semrush traffic is modeled third-party data. Malka's non-branded share comes from a manual keyword classification; Adorn Pili uses branded/near-branded share, so the two measures are directional rather than directly comparable.
Key findings
Independent jewelry brands are building discovery on multiple fronts.
Independent ecommerce
90%
Owning the checkout is the norm here: discovery can end on a page the brand controls.
104 of 115 researched brands
Found & Form · Found & Form Discovery Map · n = 115
Etsy
31%
Etsy presence is far from universal in this sample, which was partly built from Etsy research.
45 of 143 researched brands
Found & Form · Found & Form Discovery Map · n = 143
Etsy and own ecommerce
21%
Selling in both places is uncommon: marketplace reach alongside a store the brand controls.
24 of 112 researched brands
Found & Form · Found & Form Discovery Map · n = 112
Each figure is the share of brands Found & Form has researched for that signal, not of all independent jewelry brands. A figure publishes once at least 70% of the 146 brands in the sample have been researched for it and at least 20 brands have a definite answer.
The discovery gap
Independent jewelry is hard to find if you don't already know the brand.
Search and AI discovery depend on something more difficult than ranking for a brand name: appearing when a shopper searches for a product, material, style or category without knowing which brand to ask for. Found & Form's research shows that gap is real.
A brand can have a beautiful site, sell successfully and rank for its own name while remaining difficult to encounter through non-branded search and AI recommendations. Found & Form measures that discovery gap and identifies what can make a brand easier for search engines and AI systems to discover, understand and recommend.
Editorial
37%17 of 46 researched
Physical retail
41%20 of 49 researched
Owned ecommerce
71%32 of 45 researched
Each bar is the share of brands with a firm determination for that channel where discovery was observed. A channel is shown only after at least 70% of the fixed cohort has a firm result and the denominator is at least 20. AI Recommendations follows the same publication rule. An AI observation means a brand surfaced from a qualifying non-branded discovery prompt; it does not mean the brand has broad AI visibility. Most brands in the sample have not yet been confirmed this way.
Etsy vs. owned ecommerce
Etsy is usually a complement, not a replacement.
- 69%Own ecommerce only77 of 112 brands
- 21%Etsy + own ecommerce24 of 112 brands
- 10%Neither: sells through stockists or by appointment11 of 112 brands
Search vs. AI discovery
Search visibility isn't AI visibility.
Ranking well in traditional organic search doesn't necessarily mean a brand is recommended when someone asks an AI about a category. Found & Form measures the two separately, and counts only non-branded, category-level AI results as discovery. Mentions that come from people typing the brand's own name are tracked apart from that.
Split result
Stone and Strand
Category: evil eye bracelet
- Google · non-branded
- Google US: 'evil eye bracelet' #8 (22,200/mo), from the Discovery Index record
- AI recommendations
- 1 AI mention
Category: tiny diamond jewelry
- Google · non-branded
- Google US: 'tiny diamond' #4 (6,600/mo), from the Discovery Index record
- AI recommendations
- 33 AI mentions
Same brand, different categories: Google strength in one category does not predict AI presence in another.
View brand research →
Search vs. AI
Loren Stewart
Category: safety pin jewelry
- Google · non-branded
- “safety pin earrings”: #1, 1,900/mo
- AI recommendations
- 8 AI mentions
Earlier study observation, for context only: 0 Loren Stewart prompts when filtered for the brand. (Discovery Study No. 13 (Semrush Prompt Research, US, all platforms), Oct 1, 2026). The queries were not identical, so this is not a measured change over time.
A study looked at a similar territory with different queries. It is shown as context, not as change over time.
View brand research →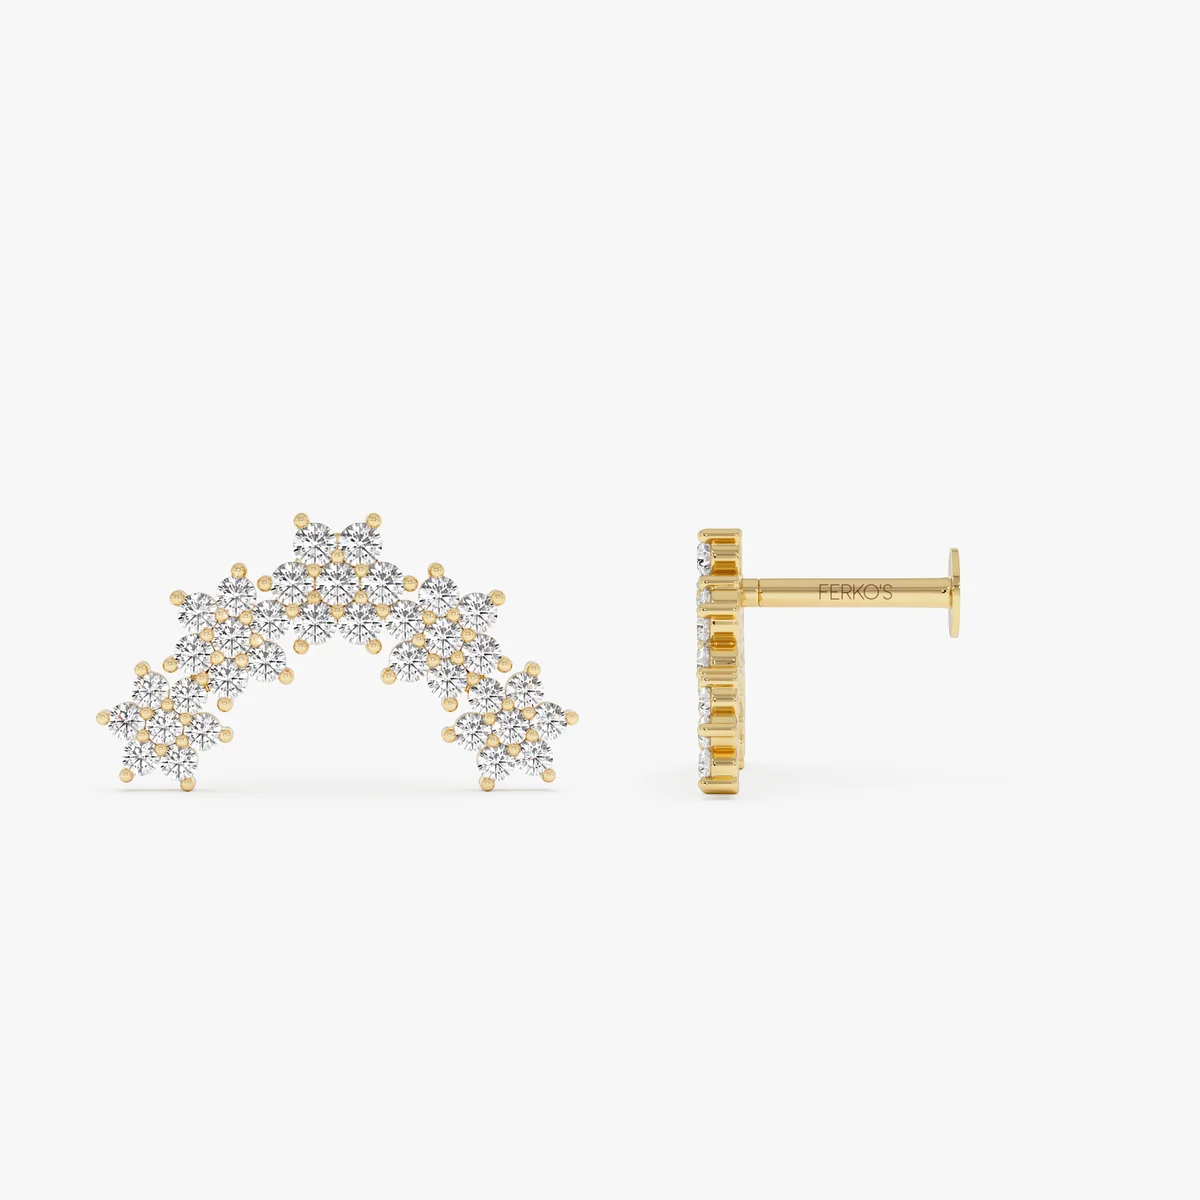
Search vs. AI
Ferko's Fine Jewelry
Category: 14k gold rings
- Google · non-branded
- Google US: 'ring 14kt gold' #4 (14,800/mo), from the Discovery Index record
- AI recommendations
- 53 AI mentions
In these categories, Google strength and AI presence line up. They are still measured separately.
View brand research →
Search vs. AI
Pyrrha
Category: talisman jewelry
- Google · non-branded
- Google #1 for 'talisman necklace', 'talisman necklaces', 'black onyx talisman', 'garnet talisman', 'talisman rings' (Discovery Study No. 11)
- AI recommendations
- 18 AI mentions
In these categories, Google strength and AI presence line up. They are still measured separately.
View brand research →
Search vs. AI
Sydney Evan
Category: shark earrings
- Google · non-branded
- Google US: '14k yellow gold shark stud earrings' #5 (6,600/mo), from the Discovery Index record
- AI recommendations
- 13 AI mentions
In these categories, Google strength and AI presence line up. They are still measured separately.
View brand research →
Search vs. AI
Zoe Lev
Category: initial necklace
- Google · non-branded
- Google US: 'gold initial necklace' #5 (8,100/mo), from the Discovery Index record
- AI recommendations
- 65 AI mentions
In these categories, Google strength and AI presence line up. They are still measured separately.
View brand research →AI results come from Semrush AI Visibility (US) on the dates shown and vary by platform, prompt and date. Each card shows only categories where both a Google result and an AI result were recorded.
Brand research
What the research found, brand by brand.
Each card leads with the most interesting discovery finding recorded for the brand. Open a card for the full evidence, dates and sources. Inclusion reflects research coverage, not endorsement.
146 of 146 brands
More filters
- Observed
- Not observed
- Not confirmed
Diamondrensu
Marketplace-first
- Marketplace: Observed
- Search: Observed
- AI Recommendations: Observed
- Editorial: Not observed
- Retail: Observed
- Owned Ecommerce: Observed
Non-branded search
Ranks #2 for “amethyst crystal”
#2, 27,100/mo · Semrush, Oct 3, 2026
Loren Stewart
Los Angeles, California, United States · Designer-led
- Marketplace: Observed
- Search: Observed
- AI Recommendations: Observed
- Editorial: Observed
- Retail: Observed
- Owned Ecommerce: Observed
Non-branded search
Ranks #1 for “safety pin earrings”
#1, 1,900/mo · Semrush, Oct 3, 2026
Remeinz
Designer-led
- Marketplace: Not observed
- Search: Observed
- AI Recommendations: Not observed
- Editorial: Not confirmed
- Retail: Observed
- Owned Ecommerce: Observed
Non-branded search
Ranks #9 for “black stone silver bracelet”
#9, 170/mo · Semrush, Oct 3, 2026
Aliita
Designer-led
Editorial
Independent editorial coverage
wwd.com
Anita Ko
Designer-led
Editorial
Independent editorial coverage
forbes.com · jckonline.com · wmagazine.com
Boochier
Designer-led
Editorial
Independent editorial coverage
tatlerasia.com
Brooke Gregson
Designer-led
Editorial
Independent editorial coverage
jckonline.com
Cece Jewelry
Designer-led
Editorial
Independent editorial coverage
jckonline.com · forbes.com
Celine Daoust
Designer-led
Retail
Stocked by third-party retailers
celinedaoust.com
Charmco
New York, New York, United States · Designer-led
- Marketplace: Not observed
- Search: Observed
- AI Recommendations: Observed
- Editorial: Observed
- Retail: Observed
- Owned Ecommerce: Observed
Editorial
Independent editorial coverage
jckonline.com
Heather B. Moore
Designer-led
- Marketplace: Not observed
- Search: Observed
- AI Recommendations: Observed
- Editorial: Observed
- Retail: Observed
- Owned Ecommerce: Observed
Editorial
Independent editorial coverage
rapaport.com · clevelandmagazine.com
Hirotaka
Japan · Designer-led
Editorial
Independent editorial coverage
jckonline.com
About the research
Independent insight for a changing discovery landscape.
The Found & Form Discovery Map analyzes patterns in the underlying dataset mapping how independent jewelry brands are encountered across search, AI recommendations, marketplaces, editorial, retail and owned ecommerce.
The report is built from direct Found & Form brand research and published Discovery Studies. It analyzes discovery patterns rather than ranking brands by popularity.
Use and citation
© 2026 Found & Form. All rights reserved. The Discovery Map and its findings are original research and are not released under an open license. You may quote short excerpts and cite individual findings with attribution to Found & Form and a link to this page. To republish, reuse the underlying data, or use it commercially, email dana@foundandform.studio first.
Continue exploring
The State of Independent Fine Jewelry Brands 2026
What founders themselves report about discovery, customer acquisition, Etsy, ecommerce, search, social and AI. Survey research, reported separately from this Discovery Map.
Coming soon
Independent Jewelry Brand Index
Individual brand intelligence: who each brand is, what it makes, where it sells and how it appears to get discovered.
Discovery Studies
Dated, sourced studies mapping where a single brand can be encountered across search, creators, editorial, owned channels and commerce.
Beyond Etsy
Research into how marketplace jewelry sellers build discovery outside the marketplace.
Coming soon